Shopping for a mortgage
Mortgage Broker vs. Bank: What Changes When Lenders Compete
A bank can only offer its own loan programs. A broker compares many lenders for the same file. Here's when that difference matters, and when it doesn't.
By Abe Hakawati, NMLS #341393 · Published November 21, 2026 · 5 minute read
The basic difference
A bank or retail lender offers its own loan programs, priced by its own rules. If your file doesn't fit, the answer is usually no, or a program that costs more than it should.
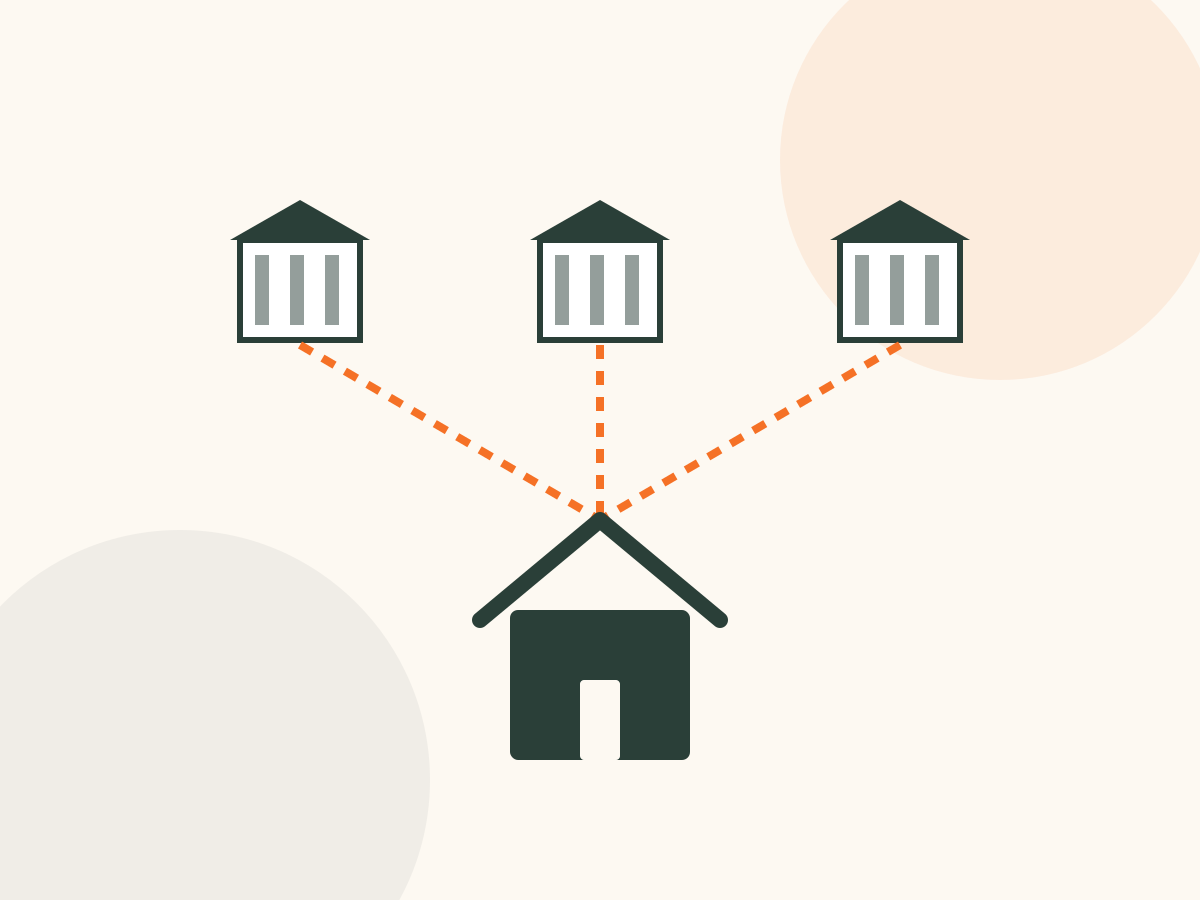
A mortgage broker is licensed to arrange loans with many wholesale lenders. The broker takes one application and one set of documents, compares programs and pricing across lenders, and submits the file to the one that fits best. The lender still underwrites and funds the loan.
When comparing lenders matters most
For a simple file, such as a W-2 borrower with strong credit and 20% down, many lenders will offer similar terms. The bigger differences show up when the file has something unusual:
- Self-employed income, where some lenders accept bank statements instead of tax returns.
- Investment properties, where DSCR loans qualify on rent rather than personal income.
- Condos, which some lenders won't touch because of the building's budget, insurance or litigation. See our guide to buying a Florida condo.
- Higher loan amounts, where jumbo rules vary widely.
- Recent credit events, job changes or foreign national buyers.
What about cost?
Broker compensation is disclosed on your Loan Estimate and Closing Disclosure, just like a bank's origination charges. Because wholesale pricing is competitive, a broker's total cost is often similar to or lower than a retail lender's. The only fair way to know is to compare Loan Estimates for the same loan amount, rate lock period and points.
Look at the APR and the total in Section A (origination charges) and Section B (services you can't shop for), not just the rate.
When a bank may be the better fit
Some banks offer relationship discounts for large deposits, or portfolio loans they keep on their own books for unusual properties. If your bank offers one, bring the Loan Estimate to us and we'll tell you honestly whether we can beat it.
Questions to ask any loan officer
- How many lenders will you compare for my file?
- What is the total cost, including points and fees, in writing on a Loan Estimate?
- How long is the rate lock, and what happens if closing is delayed?
- Who will I talk to if something changes during underwriting?
- What is your NMLS number? You can look it up at NMLS Consumer Access.
Common questions
Does a broker fund my loan?
No. The lender underwrites and funds the loan. The broker compares lenders, prepares and submits the file, and manages the process through closing.
Will I pay more with a broker?
Not necessarily. All compensation is disclosed on the Loan Estimate. Compare the estimates side by side for the same loan terms.
Can a broker help if a bank already turned me down?
Often, yes. Lenders have different guidelines for income, credit, property type and loan size, so a file one bank declines may fit another lender's program.
Get numbers for your situation
We compare options from 100+ wholesale lenders: home loans in Florida, Texas and California, and investment and commercial loans nationwide.
This article is for general educational purposes and is not a commitment to lend or legal, tax or financial advice. Programs, limits, rates and guidelines change and depend on the complete application. Owner-occupied home loans are available only in Florida, Texas and California; investment and commercial loans are available nationwide.